LinkedIn profile for David Coleman David Coleman
Founder & Renewable Energy Author, kilowatts.uk
LinkedIn profile for David Coleman David Coleman
Founder & Renewable Energy Author, kilowatts.uk
Article
In practice, the most relevant relief for many SMEs is the Annual Investment Allowance, known as AIA.
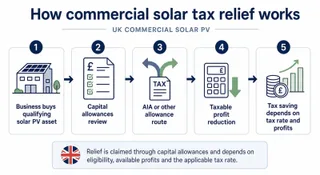
In practice, the most relevant relief for many SMEs is the Annual Investment Allowance, known as AIA.
As at 20 October 2026, plan on the rules already set out in this guide. Commercial solar tax relief in the UK is still a capital allowances claim, made through the accounts and the tax computation, not a grant and not a discount on the installer's invoice. For many SMEs the first route is still the Annual Investment Allowance, at £1 million for a 12-month chargeable period, shared or restricted where businesses are connected, under common control, or in a group. Full expensing is still a company-only route for qualifying new and unused plant. Solar PV that is not covered by AIA is still commonly special-rate expenditure: a 50% first-year allowance where that company route applies, otherwise writing down allowances at 6% a year. The super-deduction remains closed. It ended on 31 March 2023. This update does not add a new relief. Ask your accountant to confirm the treatment against the return you will actually file.
The useful check now is timing inside the current accounting period. AIA is a limit on qualifying expenditure, not a rebate paid when the panels are installed. Expenditure is generally incurred when the business has an unconditional obligation to pay, so a deposit, the start of a hire purchase agreement, and completion can fall in different periods. If other plant has already used most of the allowance, part of the solar cost may be relieved more slowly. That changes cash flow. It does not, by itself, decide whether the project is sound.
VAT and business rates remain separate from the capital allowance claim. Ordinary commercial solar installations are still normally charged at 20% VAT. The 0% energy-saving materials treatment is still mainly for residential and certain charitable buildings, not standard commercial premises. In England, eligible onsite renewable plant and storage can still be kept out of a business rates increase until 31 March 2035, but Scotland, Wales, and Northern Ireland are separate, and plant aimed mainly at export can be treated differently. Do not put a local grant into the after-tax cost unless the award, its conditions, and the effect on qualifying expenditure have all been confirmed. Ownership still decides who may claim. An outright purchase, or finance that meets the capital allowances conditions, is not the same as a power purchase agreement. Under a typical PPA the provider owns the plant and is usually the party that may claim allowances. The customer buys electricity and should not assume it can also claim AIA. If you are still comparing contract types, size the system from half-hourly use first, then compare commercial solar options alongside written advice from your accountant. Larger sites can make the same check against industrial solar options. This note is not tax advice.
The update above is what has changed since then.
Commercial solar tax relief in the UK usually means claiming capital allowances on the cost of a business solar PV system. In practice, the most relevant relief for many SMEs is the Annual Investment Allowance, known as AIA, which can give 100% tax relief on qualifying plant and machinery expenditure up to the annual limit.
For a profitable UK business, that can make a material difference to the after-tax cost of installing commercial solar panels. However, the value depends on the business's eligibility, taxable profits, corporation tax or income tax rate, VAT position, ownership model, finance structure, accounting period, group position, and whether the system is genuinely used for the trade.
The key point is that commercial solar tax relief is not normally a grant and it does not usually reduce the installer's invoice. It is normally claimed through the accounts and tax computation after the business has incurred qualifying expenditure. A profitable limited company may see a corporation tax saving. A loss-making business may need to wait to benefit, depending on how losses are used. For most commercial buyers, tax relief improves the return on investment but should not be the only reason to install solar. The strongest projects still tend to have:
Businesses comparing quotes can start by reviewing commercial solar options alongside the tax position. This guide explains the main UK tax relief routes for business solar panel installation, including AIA, full expensing, writing down allowances, VAT, business rates, export income, grants, and ownership structures. It is a practical guide, not tax advice. Businesses should confirm the tax treatment with their accountant or tax adviser before committing to a purchase, especially where grants, leases, landlords, group companies, mixed-use buildings, or power purchase agreements are involved.
The Annual Investment Allowance allows many businesses to deduct the full cost of qualifying plant and machinery from taxable profits in the year of expenditure, subject to the AIA limit. The current AIA limit is £1 million per year, although it can be shared or restricted where businesses are connected, under common control, or part of the same group.
Commercial solar PV bought for use in a business can usually fall within plant and machinery capital allowances. That means a limited company, sole trader, or most partnerships may be able to claim AIA for solar panels where the qualifying conditions are met.
A simple example is a trading company buying a £100,000 qualifying solar PV system. If the full cost is covered by AIA, the business may be able to deduct £100,000 from taxable profits. If the company pays corporation tax at 25%, the tax saving could be up to £25,000. At a 19% corporation tax rate, the saving could be up to £19,000. AIA does not mean HMRC gives the business the full cost back. The business still has to fund the installation. The tax value is the deduction multiplied by the relevant tax rate, and the timing depends on taxable profits, accounting periods, instalment payments, and tax payment dates. For buyer-intent purposes, the useful question is not simply 'do commercial solar panels qualify for tax relief?' but 'how much of this specific project cost qualifies, when can my business use the deduction, and how does that change the after-tax payback?'
A commercial solar tax claim is usually handled through the accounts and tax computation, not through the installer's quote. The installer supplies the system and invoice, then the business and its adviser identify which costs qualify and which allowance route applies.
In a typical project, the practical sequence is straightforward but the details matter.
This is why accurate documentation matters. A single 'solar installation' invoice may be acceptable commercially, but for tax purposes it is useful to understand what has been supplied, what is part of the PV plant, and what may be building work or another category. A well-documented commercial solar quote should ideally make it clear whether the price includes items such as scaffolding, roof strengthening, asbestos works, DNO application support, battery storage, metering upgrades, or EV charging infrastructure. Those items may still be commercially sensible, but they should not automatically be assumed to have the same tax treatment as the solar PV array.
A business buys a commercial solar PV system costing £100,000 excluding VAT. If the full amount qualifies for AIA and the business has enough AIA capacity and taxable profit, the capital allowance deduction may be £100,000.
At a 25% corporation tax rate, that deduction could reduce corporation tax by up to £25,000. The effective after-tax capital cost before VAT and finance effects would then be £75,000. At a 19% corporation tax rate, the tax saving could be £19,000, giving an effective after-tax capital cost before VAT and finance effects of £81,000.
The same installation can therefore produce different tax outcomes for different businesses. A profitable limited company with unused AIA may receive a clear corporation tax benefit. A company with existing losses may create or increase a loss rather than receive an immediate cash saving. A group of connected companies may have to share the AIA limit. A partially exempt business may not recover all VAT, changing the effective project cost. A grant-funded project may have a lower amount of qualifying expenditure for capital allowances. It is also important to separate tax saving from project payback. Solar payback is mainly driven by how much generated electricity the business uses on site, the import price avoided, the export price received, system performance, maintenance, degradation, insurance requirements, and finance costs. Tax relief improves the numbers, but it does not rescue a badly sized or poorly specified system. For example, a warehouse operating five days a week may have strong weekday self-consumption but high weekend exports. A cold store running continuously may use a much higher proportion of the generated power on site. Both may be eligible for tax relief, but their commercial solar return on investment can be very different.
The solar PV plant itself is commonly the core qualifying expenditure. A commercial system may include panels, inverters, mounting equipment, cabling, isolators, metering, monitoring hardware, design, commissioning, and DNO-related work.
Some items can be more nuanced. Roof repairs, roof replacement, structural strengthening, building alterations, groundworks, canopies, fencing, grid reinforcement, EV chargers, batteries, and professional fees may need separate review. Some may qualify for capital allowances, some may have a different relief profile, and some may be treated as building-related expenditure depending on the facts.
Businesses planning related upgrades should review items such as commercial EV charger installation and commercial solar battery storage separately from the PV array where appropriate. This distinction is especially important on older commercial roofs. If a roof needs replacement soon, it is often better to deal with the roof before installing panels. Removing and reinstalling an array later can add cost, disrupt operations, and affect warranties. Roof works do not automatically follow the same tax treatment as the solar plant. Different site types can create different tax and design questions.
Routine maintenance is normally considered separately from the capital purchase. Servicing, repairs, insurance, monitoring subscriptions, and cleaning are operating costs, although larger replacements or improvements may need specific accounting and tax treatment.
AIA is often the first allowance to consider, especially for SMEs, but it is not the only route. Full expensing is another capital allowance route for companies, and it can apply to qualifying new and unused plant and machinery. It is not available to sole traders or ordinary partnerships.
Full expensing is mainly relevant where AIA is unavailable, already used, or not the best route. Main-rate plant can qualify for 100% full expensing, while special-rate plant can qualify for a 50% first-year allowance. Solar panel expenditure not covered by AIA is commonly treated as special-rate expenditure, which can otherwise attract writing down allowances at 6% per year.
The classification of components can affect how quickly relief is received. Main-rate writing down allowance is currently 18% per year, while special-rate writing down allowance is currently 6% per year. This is one reason larger projects, group companies, and businesses already using their AIA on other plant should take advice before assuming full first-year relief applies to everything. A practical example is a company that has already used most of its AIA on machinery, vehicles, or equipment in the same accounting period. If it then installs a larger solar PV system, part of the project may fall outside AIA and may receive relief more slowly. That does not necessarily make the project unattractive, but it changes the cash-flow profile and the after-tax payback. The old super-deduction is no longer available for new projects. It ended on 31 March 2023, but it still appears in outdated solar articles and can cause confusion. New commercial solar decisions should be based on the current UK capital allowance rules, not on expired incentives.
VAT is often misunderstood in commercial solar projects. Capital allowances and VAT are separate tax issues. Most standard commercial solar installations are subject to 20% VAT, and the 0% VAT relief for energy-saving materials is mainly relevant to residential and certain charitable buildings rather than ordinary commercial premises.
A VAT-registered business using the solar system for taxable business activities can usually reclaim input VAT, subject to the normal VAT rules. Partially exempt businesses may recover only part of the VAT. A business that is not VAT registered will normally bear the VAT cost.
This affects the capital allowance claim. If VAT is recoverable, capital allowances are normally based on the net cost. If VAT is not recoverable, the unrecovered VAT may form part of the cost considered for tax relief. VAT can also affect cash flow. Even where VAT is recoverable, the business may have to pay the installer first and recover VAT through its return later. For large systems, that timing difference can matter. Mixed-use buildings need extra care. A property with commercial and residential areas, or a charity with both qualifying and non-qualifying uses, may not fit the simple 'standard commercial premises' position. The installer's VAT treatment should be checked before signing, because correcting an incorrect VAT assumption after installation can be difficult.
Business rates are separate from capital allowances. In England, there is a green plant and machinery exemption for eligible onsite renewable generation and storage until 31 March 2035. This can prevent eligible solar plant from increasing the rateable value, but systems mainly used for export may be treated differently.
Scotland, Wales, and Northern Ireland have separate rating rules, so businesses should not assume the English position applies UK-wide. Larger export-led systems can also involve more rating complexity than a straightforward self-consumption rooftop array.
Export income is normally taxable business income. If a business sells surplus electricity to the grid through a Smart Export Guarantee tariff, export contract, or commercial power purchase arrangement, that income should be considered in the accounts. Savings from using self-generated electricity are not a separate tax-free income stream either. They reduce electricity costs and can increase accounting profit compared with buying all electricity from the grid. Grants can reduce the amount qualifying for capital allowances. If a business receives a subsidy towards the solar installation, the tax-relievable expenditure may be lower. This is one reason grant-funded projects should be reviewed carefully before the business forecasts its after-tax return. Businesses should also check whether a grant comes with conditions, such as approved suppliers, minimum performance standards, reporting obligations, subsidy control requirements, or restrictions on claiming other support. Local schemes can open and close, so it is safer to check live eligibility than rely on old online grant lists.
The business that owns the solar asset is usually the party that may claim the capital allowances, assuming the other conditions are met. This sounds simple, but commercial solar ownership can become complicated.
If a business buys the system outright, the link between expenditure and tax relief is usually clearest. Asset finance or hire purchase may still allow capital allowances where the arrangement meets the relevant conditions. Finance costs, interest, and capital allowances are separate points.
Under a solar power purchase agreement, the customer usually does not own the solar system. The PPA provider owns, operates, and sells electricity from the system, so the provider is usually the party claiming capital allowances. The customer gets electricity under the contract rather than tax relief on the asset. This is a common buyer-intent issue. A business searching for 'commercial solar tax relief UK' may be comparing outright purchase, finance, and PPA offers. Those options can all reduce electricity costs, but they do not produce the same tax outcome. A PPA may require little or no upfront capital, but the customer should not assume it can also claim AIA on an asset it does not own. Tenanted buildings need extra care. A tenant may need landlord consent, lease variations, roof access rights, insurance approval, metering arrangements, and clarity over what happens at lease expiry. A short lease can undermine the investment case even if the tax relief looks attractive on paper. Landlord-owned systems create different issues. The landlord may own and claim relief on the asset, while tenants may benefit through electricity arrangements or service charge structures. The tax and legal position should be aligned before installation, not after.
Commercial solar should be sized from electricity demand, roof constraints, and grid limits rather than tax relief alone. Annual electricity consumption is not enough for accurate sizing because it hides daily and weekly demand patterns. Half-hourly electricity data is much more useful because it shows when the site actually uses power.
A system sized only on annual kWh can overproduce at weekends, bank holidays, summer shutdowns, or quiet trading periods. Exported electricity usually earns less than the avoided import cost, so a highly export-heavy system can have weaker economics even where the capital allowance claim is attractive.
Roof design also matters. South-facing roofs usually maximise annual generation, but east-west layouts can suit commercial buildings with long daytime loads because they spread generation across more of the working day. A lower annual yield can still be commercially sensible if it improves self-consumption and reduces export. Some technical terms are worth clarifying.
Installer-level details can materially affect cost and performance. Inverter placement affects cable runs, ventilation, access, and losses. Flat-roof ballast needs wind-load calculations. Fragile or asbestos roofs can make installation difficult or uneconomic. Fire service access routes, insurer requirements, bird protection, safe maintenance access, and waterproofing details should all be considered before the tax calculation is treated as final. A pre-installation review may also include commercial electrical inspections where the existing electrical infrastructure needs checking.
Commercial solar tax relief tends to be most valuable where the business has taxable profits, sufficient AIA capacity, and a technically sound solar project. It is especially useful where the business is already planning capital investment and can compare the solar system against other plant and machinery spending.
Strong-fit projects often share several features.
The business has significant daytime electricity demand. The building has a sound roof with a long remaining life. The owner or tenant has secure long-term site occupation. The business has taxable profits that can use the allowance. The grid connection can accept the proposed system without costly delays. The system is sized around half-hourly usage data. A warehouse, factory, cold store, office, school, leisure centre, farm, or commercial unit can all be suitable, but the answer depends on actual consumption patterns. A high-use site running six or seven days a week will often have a stronger self-consumption case than a site that shuts down for long periods. Here are three simplified project scenarios. Larger manufacturing and logistics sites may also want to compare industrial solar options if the project is closer to an industrial-scale installation. VAT is recoverable or properly allowed for in the budget. The ownership model matches the expected tax treatment. The project is not relying on tax relief to compensate for weak technical fundamentals. Cold store with continuous load - Often a strong solar candidate because refrigeration demand can support high on-site use during the day and across weekends. Office with weekday daytime demand - May work well, especially with east-west roof layouts, but weekend export and holiday periods should be modelled. Seasonal site or low weekend-use warehouse - May still be viable, but oversizing can lead to more export and a longer payback unless export terms are strong.
Commercial solar is not automatically suitable just because tax relief is available. A loss-making business may not receive an immediate cash benefit from AIA. The claim can create or increase a tax loss, but using that loss depends on the normal tax rules and the business's future profits.
The case can also be weaker where the roof is shaded, close to replacement, structurally limited, or difficult to access. If significant roof or grid work is required, the total project cost may rise and the tax treatment of those additional works may not be as favourable as the PV plant itself.
Businesses should be cautious where they have already used much of their AIA allowance on other investment, where group companies share the AIA limit, or where the solar project is funded by a grant. Non-VAT-registered and partially exempt businesses should also model VAT carefully because unrecovered VAT increases the effective cost. Short leases are another common problem. If the business may leave the building before the solar system has delivered enough savings, the tax relief may not compensate for the commercial risk. Lease rights, reinstatement obligations, and landlord approvals can be just as important as the tax calculation. Grid constraints can also weaken the case. A site may have excellent roof space and strong daytime demand, but if the DNO restricts export or requires costly reinforcement, the system size may need to be reduced or export limitation added. That does not necessarily prevent installation, but it changes the design and financial model.
A common mistake is treating AIA as a rebate. AIA can reduce taxable profits, but it does not mean a £100,000 system gives £100,000 back from HMRC. The tax saving depends on the tax rate and the business's ability to use the deduction.
Another mistake is assuming all commercial solar gets 0% VAT. Standard commercial premises are normally subject to 20% VAT on solar installations, although VAT-registered businesses may be able to reclaim input VAT where the system is used for taxable business activities.
Businesses also sometimes assume the super-deduction still applies. It does not apply to new commercial solar installations now because it ended on 31 March 2023. Other mistakes are more practical than tax-related. Sizing the system from annual consumption alone. Ignoring weekend, seasonal, or shutdown-period export. Installing on a roof that needs near-term replacement. Assuming DNO approval will be quick or unrestricted. Forgetting that export income is taxable. Signing a PPA and expecting to claim capital allowances. The safest approach is to combine a technical survey, half-hourly energy analysis, grid review, and tax review before committing to the final system size and contract structure. Treating every roof or structural cost as automatically qualifying. Failing to check insurer and fire safety requirements early. Comparing quotes without checking whether batteries, scaffolding, monitoring, or grid works are included. Assuming the cheapest inverter design is the best option for a shaded or complex roof. Forgetting to align the solar purchase date with the business's accounting period and AIA position.
A good commercial solar assessment needs both tax information and engineering information. If either side is missing, the forecast can be misleading.
Before seeking final advice, gather the following.
Installed system cost excluding VAT. VAT recoverability position. Business structure and tax rate. Forecast taxable profits. Existing AIA usage in the accounting period. Group or associated company position. This information helps avoid two common problems: an attractive tax estimate for a poor solar design, or a good technical design that does not deliver the expected after-tax cash flow. Proposed ownership and finance method. Accounting period end date. Half-hourly electricity consumption data. Import and export electricity prices. Roof age, condition, warranty, and structural information. Lease length and landlord consent position. Grid connection capacity and export restrictions. Any grants or subsidies being considered. Existing electrical capacity and main distribution board information. Insurer requirements for solar PV, roof access, and fire safety. Whether the business is considering batteries, EV chargers, or future load growth. Any planned roof works, refurbishments, or site moves.
Tax relief is only one part of a commercial solar decision. Before choosing an installer, it is worth reviewing related areas that can materially affect the project return.
Solar PV system comparison: Businesses still choosing a supplier can compare commercial solar options. Battery storage: Sites with evening load, peak charges, or export constraints may need to assess commercial solar battery storage separately from the PV array. EV charging: Businesses electrifying fleets or adding workplace chargers should review commercial EV charger installation alongside solar generation and grid capacity. Electrical infrastructure: Older sites may need commercial electrical inspections before a solar connection is finalised. Industrial-scale projects: Larger factories, logistics sites, and high-consumption facilities may be better suited to industrial solar options.
These decisions interact. For example, adding EV chargers can increase daytime electricity use and improve solar self-consumption, but it may also require electrical upgrades. Adding battery storage can reduce export and support peak management, but the tax treatment, cost, maintenance, and control strategy should be reviewed separately.
Commercial solar tax relief in the UK is usually most effective when AIA or another capital allowance route is matched with a well-designed, self-consumption-led solar project. The tax saving can be material, but it is only one part of the decision.
The next step is to check three things in parallel.
First, confirm the likely tax treatment with an accountant using the actual ownership, finance, VAT, profit, AIA, and group position. Second, ask for a solar design based on half-hourly electricity data, not just annual usage. Third, review roof condition, grid approval, lease rights, insurer requirements, and electrical capacity before signing. If the project still looks viable, you can compare commercial solar options before choosing an installer or quote route. If those checks support the case, commercial solar can reduce imported electricity, improve long-term energy cost control, and deliver useful tax relief through the normal UK capital allowance system.
Solar comparison
Enter your postcode to assess your roof, compare solar options and get quotes from UK installers.
Choose home, business or industrial, then enter your postcode. RoboMo maps the roof and ranks panel brands by fit.
1. Postcode Start the assessment for your property.
2. Pin the roof Mark the array on the map.
3. Compare RoboMo™ builds your options.
Battery ROI tool
Enter the day rate, off-peak rate and export rate. The calculator ranks batteries in the Kilowatts shop over 10 years. Home batteries also suit offices and small commercial sites.
Reading
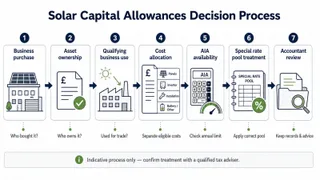
Understand capital allowances commercial solar in the UK, with clear explanations, examples, and practical next steps.
Read article
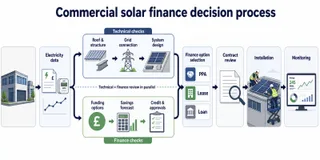
It determines: who funds the installation who owns the solar panels and associated equipment who receives the electricity savings who receives any export.
Read article
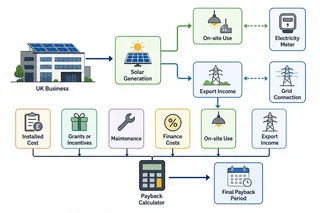
Commercial payback depends on daytime load, export rate and capex. Use site figures, not a single national year count.
Read article
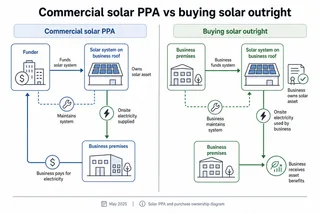
Buying commercial solar is usually better when the business can use cash or finance, expects to remain on site long term.
Read article
Write for Kilowatts.uk
Write it here under your own name. Sign in, put a profile up, and start a guide. Pay only if you want more links from your articles out to your own site.
Create a Kilowatts.uk account, or sign in if you already have one.
Put your name, photo and experience on a public author page.
Write a guide or a blog. Free authors can put one followed link to their own site in articles each month.
FAQ
Live help
Talk to RoboMo™ and get instant answers.
Live chat